


This article was automatically translated from the original Turkish version.
+1 More
Establishment | 2016 | ||||||||
|---|---|---|---|---|---|---|---|---|---|
Founder/Operator | Interbank Card Center | ||||||||
Card Types | Bank card Prepaid card Credit card | ||||||||
Application Area | POS Internet ATM Mobile payment | ||||||||
TROY is a payment system developed to meet Türkiye’s need for a domestic payment infrastructure and launched in 2016 under the umbrella of the Interbank Card Center. TROY, defined as the domestic payment method embedded on bank cards, credit cards, and prepaid cards, has been opened for joint use by financial institutions in Türkiye. Over time, it has become valid across nearly the entire domestic transaction network and, through collaborations with international card schemes, has gained availability for use abroad. Alongside its expanding user base, alignment with government institutions, and partnerships across various sectors, TROY has increasingly established a more prominent position within Türkiye’s payment systems ecosystem.
TROY logo (TROY)
The operation of TROY is managed by the Interbank Card Center A.Ş. The system was launched in 2016 as part of the financial sector’s collective effort to develop a shared payment infrastructure. The ownership structure of the Interbank Card Center determines key aspects of TROY’s governance. Sources indicate that the Central Bank of the Republic of Türkiye holds a majority stake in the Interbank Card Center, alongside varying levels of participation from public and private banks. Within this framework, TROY has been developed as a domestic card scheme enabling banks and payment institutions in Türkiye to operate in a compatible manner.
Among the motivations for developing TROY is the desire to reduce Türkiye’s dependence on international payment systems. It has been noted that sanctions targeting international card schemes and global political conditions can occasionally disrupt payment flows. In this context, the development of a domestic system has been regarded as a strategic necessity for the financial sector. TROY was officially launched in 2017 by the Interbank Card Center, and recommendations for its adoption by public institutions were issued during the same period.
Hakan Çalhanoğlu: “Pay with TROY, let our Türkiye win with you!” (Youtube-TROY)
TROY is a card scheme used on bank cards, credit cards, and prepaid cards. The system provides the infrastructure for processing, authenticating, and settling transactions between banks. It has been confirmed that all ATMs and POS terminals in Türkiye are compatible with the TROY system. This compatibility has enabled TROY-branded cards to achieve widespread usage across the country.
The authentication process for TROY cards in online and mobile transactions is facilitated through the GO – Secure Pay system. This system relies on sending a one-time password to the cardholder during the transaction, creating a security layer to protect card information. This simple verification mechanism adds an extra authentication step for online payments.
In card-based transactions, TROY functions similarly to Visa or Mastercard. Available sources state that transactions can be initiated using the card number, and authorization is completed with a one-time password sent by the issuing bank, consistent with other card schemes.
International transactions with TROY cards depend on the international payment scheme logos printed on the card’s reverse side. Collaborations with international schemes such as Discover, Diners Club, and Pulse provide usage options abroad. These partnerships have extended the card’s validity to international networks.
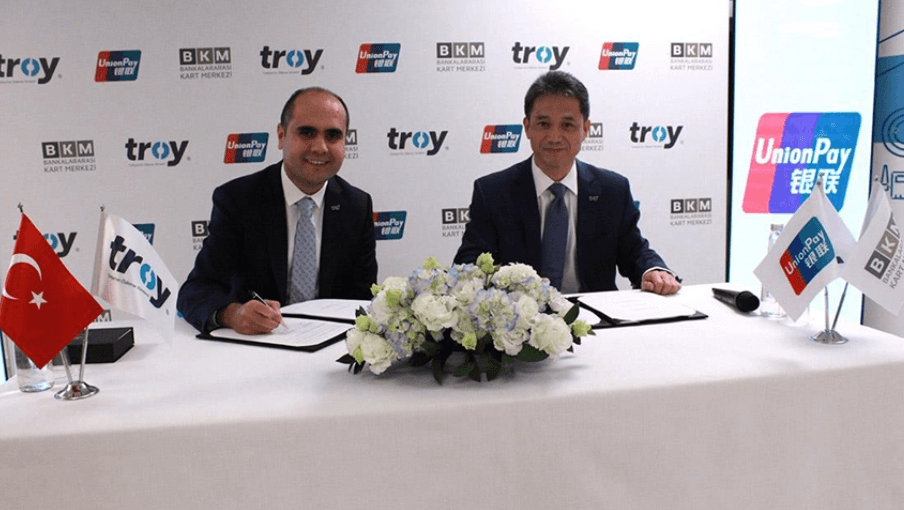
Visual of the agreement between BKM and UnionPay (AA)
TROY enables transactions at all ATMs and POS terminals in Türkiye, regardless of the issuing bank. Domestic users can withdraw cash using bank cards, make purchases with credit cards, and pay using balances loaded onto prepaid cards. It has been confirmed that TROY-branded cards can be used for e-commerce, mobile shopping, and bill payments.
Installment plans, reward points, and loyalty programs offered by banks are determined by the issuing bank. Users making purchases with TROY-branded cards are eligible to participate in these bank-specific campaigns and programs. This allows the usage experience of the card to vary directly according to the conditions offered by individual banks.
Twenty-eight banks and twenty electronic money institutions in Türkiye offer TROY-branded cards. Existing cards at these institutions can be replaced with TROY-branded cards or new TROY cards can be obtained through new applications. Card applications can be submitted through bank branches, customer service representatives, or online platforms.
Mete Gazoz: “Pay with TROY, let our Türkiye win with you!” (Youtube-TROY)
TROY’s international usage is determined by additional international scheme logos printed on the card. Sources indicate that agreements with schemes such as Discover, Diners Club, and Pulse enable international validity. Usage abroad is only possible when the relevant international logos are present on the card.
TROY has entered into partnerships with various organizations to expand its international acceptance network. The agreement with UnionPay has been noted to significantly broaden TROY’s international usage options. Such collaborations aim to increase the number of locations where the card can be used abroad.
A recent announcement confirmed that TROY cards can now be used as a payment method on Google Play. Users can add their TROY cards to their Google Play accounts to make payments for digital content. It has been stated that TROY cards are accepted during the payment method addition process in the Play Store app. This development is viewed as a step toward expanding the card’s validity on international platforms.
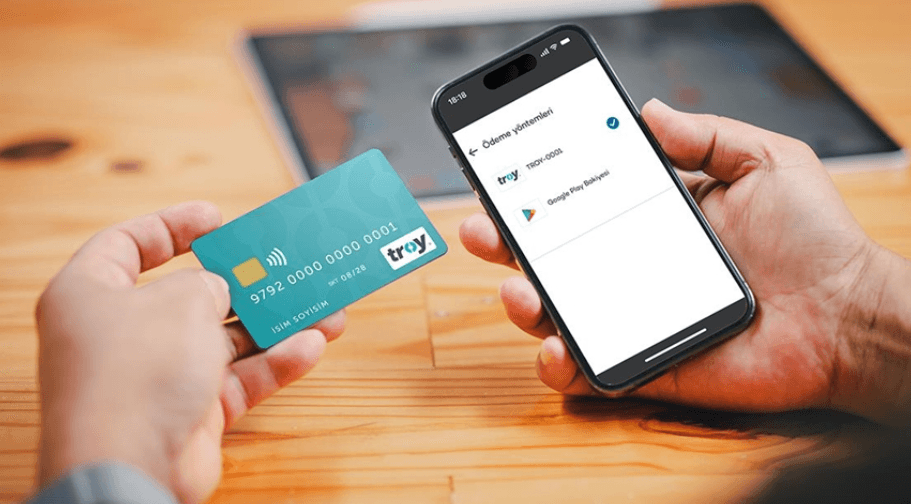
TROY card (AA)
Sources provide data on TROY’s usage across different years. As of the end of 2023, the number of users was approximately 18.8 million, and the total transaction volume reached 239.2 billion TL. According to the Interbank Card Center and other reports, user numbers have increased in subsequent periods, with rising demand.
In 2024 data, TROY’s market share reached 11.55 percent by number of cards and approximately 18 percent by total transaction volume. Analysis of available tables shows a significant increase in both the number of cards and transaction volume from 2017 to 2024. The number of cards, which stood at around two million in 2017, rose to 50 million by the end of the fourth quarter of 2024. Transaction volume increased from billions to trillions of TL during the same period.
The reasons for this growth include shifts in government policies, regulatory measures encouraging public institutions to adopt domestic payment systems, and changing societal preferences. In particular, legislative changes implemented after 2022 have accelerated the adoption rate of the domestic card scheme.
Government institutions have taken various steps to promote TROY usage. A circular published in the Official Gazette mandated that all public payments be made using domestic credit and bank cards. The circular specifies that domestic systems must be preferred for student loans, scholarship payments, social assistance, and other public disbursements.
Following this decision, public institutions have implemented measures to direct their employees, pensioners, and social assistance recipients toward using TROY cards. Sources indicate that this initiative covers millions of users and has accelerated the adoption of the domestic payment method.
A cooperation protocol signed between the Social Security Institution (SGK), PTT, and TROY further enhances card usage. Under this protocol, part of the Türkiye Century Retirees Project, retirees using TROY-branded cards will be offered special discounts, promotions, and campaign benefits. The protocol aims to facilitate and encourage retirees to use TROY cards for their financial transactions.
TROY is defined as a payment method supported by a broad banking network operating in Türkiye. Banks offering TROY cards include public banks, private banks, and participation banks.
Among the banks offering bank cards are Akbank, Halkbank, Ziraat Bankası, Vakıfbank, İş Bankası, Garanti BBVA, Yapı Kredi, and PTT, among many others. A similarly broad range of institutions offer credit cards. This widespread adoption demonstrates that TROY is recognized as a domestic standard within the banking ecosystem.
TROY cards are also available through electronic money institutions. These institutions provide prepaid card services, allowing users to load funds and use the cards for transactions.
The importance of payment systems to a country’s economy is well recognized. It has been noted that transaction fees paid to international schemes such as Mastercard and Visa represent a significant outflow, and increasing the use of domestic payment systems can help retain these funds within the country.
It is difficult to precisely calculate the total amount paid to international systems such as Mastercard and Visa, as fees vary according to bank agreements and transaction types. Nevertheless, preliminary estimates suggest that hundreds of millions of dollars are transferred abroad annually solely through transaction fees. An increase in domestic scheme usage is expected to keep these amounts within the country.
According to reported data on total card-based spending, Türkiye’s card payment volume reached approximately 3.7 trillion TL in 2022. Of this, about 2.9 trillion TL stemmed from credit card expenditures. As TROY’s share of this volume grows, data flows related to payment infrastructure are increasingly centralized within domestic systems.
TROY is a domestic payment method established to strengthen Türkiye’s financial infrastructure. Since its inception, it has been supported by banks, promoted by public institutions, and adopted by broad segments of society. The rise in card-based transactions, driven by government policies, international developments, and digitalization, has significantly expanded TROY’s usage volume. Its comprehensive coverage of the domestic ATM and POS network, combined with international partnerships, has strengthened TROY’s position within the payment systems landscape.
AA Haber. "SGK, PTT ve TROY Arasında Emekliler İçin İşbirliği Protokolü İmzalandı." Accessed November 13, 2025.http://v.aa.com.tr/3289943
AA Haber. "TROY Kartlar Artık Google Play'de Kullanılabilecek." Accessed November 13, 2025.http://v.aa.com.tr/3539005
BKM. "TROY." Bankalararası Kart Merkezi, Accessed November 13, 2025.https://bkm.com.tr/en/products-and-services/troy-en/
CNBCE. "TROY Nedir? Neden Kuruldu? Sahibi Kim? TROY’un Pazar Payı Ne?" CNBCE, Accessed November 13, 2025.https://www.cnbce.com/fintech/troy-nedir-neden-kuruldu-sahibi-kim-troyun-pazar-payi-ne-h8585
PayU Global. “Troy – Payment Methods Encyclopedia.” PayU Global, Accessed November 13, 2025.https://corporate.payu.com/troy/
Platin Online. "TROY Kart Nedir, Ne İşe Yarar? TROY Karta Nasıl Geçilir?" Platin Online, Accessed November 13, 2025.https://www.platinonline.com/bankacilik/troy-kart-nedir-ne-ise-yarar-troy-karta-nasil-gecilir-1089949
TROY Ödeme – Bankalararası Kart Merkezi. "TROY Hakkında." TROY Ödeme, Accessed November 13, 2025.https://www.troyodeme.com/tr/troy-hakkinda/hakkimizda
TRT Haber. "7 Soruda Türkiye’nin Ödeme Yöntemi: TROY." Accessed November 13, 2025.https://www.trthaber.com/foto-galeri/7-soruda-turkiyenin-odeme-yontemi-troy/60751/sayfa-1.html
Establishment | 2016 | ||||||||
|---|---|---|---|---|---|---|---|---|---|
Founder/Operator | Interbank Card Center | ||||||||
Card Types | Bank card Prepaid card Credit card | ||||||||
Application Area | POS Internet ATM Mobile payment | ||||||||
No Discussion Added Yet
Start discussion for "TROY (Türkiye's Payment Method)" article
Establishment and Corporate Structure
Technical Infrastructure and Operational Principles
Domestic Usage Areas
International Usage Opportunities and Partnerships
User Base and Card Transaction Statistics
Government Policies and Regulations Promoting TROY Usage
TROY’s Position Among Banks and Payment Institutions
Financial Data and Impact on the Payment System
